Analysts: Macau operations are cushioning MGM’s US weakness

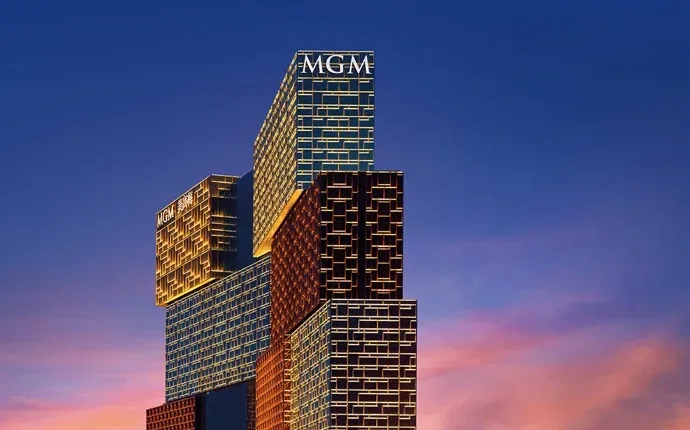
Analysts said that MGM Resorts International’s Macau business is cushioning weaker US operations.
They reached this conclusion after the company released its third-quarter results late last week.
MGM China captured a record 17.1% share of Macau’s casino gross gaming revenue in the quarter, according to JPMorgan and Texas Capital Securities. Texas Capital said its share reached 19.2% in September, noting that favorable gaming results helped.
Quarterly net revenue rose about 5% year over year to US$1.14 billion (MOP9.12 billion). However, adjusted property earnings before interest, taxes, depreciation, amortization, and rent fell 7% to US$264 million (MOP2.11 billion), according to MGM Resorts.
“While the third quarter of 2026 share partially benefited from high hold (luck factor), MGM market share momentum clearly continues, in our view,” Texas Capital wrote Thursday.
Texas Capital said that access to Greater China’s premium-mass customers gave MGM China a customer base distinct from the group’s US properties, providing a buffer against softer operating trends in the US.
Offering a different perspective, Seaport Research Partners notes that property EBITDA before license fees increased 0.6% year over year. Adjusted for VIP hold, it rose 4.7%, with favorable mass-market hold also supporting performance.
CreditSights highlighted cash generation rather than reported earnings, estimating third-quarter free cash flow between US$230 million (MOP1.84 billion) and US$240 million (MOP1.92 billion). Net leverage declined to 1.36x trailing annual EBITDA, down from 1.44x in June.
On MGM’s Japan project, JP Morgan highlighted MGM Osaka as offering considerable long-term value, but its opening remained beyond the investment horizons of many public-equity investors.
Seaport likewise recognized Japan’s potential but assigned the project no value within its current MGM Resorts valuation.


Leave a reply
You must be logged in to post a comment.